By James Schulze
This article discusses the 2027 market outlook for MCA and business funding and three developments companies will want to consider. It explains the four primary types of MCA leads and their pricing to help funding companies plan their lead spend. It also offers insights on three process changes companies can make to more effectively convert their MCA leads.
The merchant cash advance (MCA) market enters 2027 with continued demand for business funding and growing competition for qualified merchants. Funding companies must decide where to invest their marketing budgets, which leads to buy, and how to convert those opportunities into funded deals.
Since 2005, The Leads Warehouse has spent more than 20 years helping businesses develop lead acquisition strategies. For MCA buyers, the opportunity in 2027 is not simply purchasing more leads. It is matching the right lead sources to the right sales processes.
MCA market outlook for 2027 and what the data shows
The Federal Reserve’s 2026 Report on Employer Firms – which is based on findings from the 2025 Small Business Credit Survey – found that 60% of small employer firms sought financing during the previous year. A total of 38% applied for a loan, line of credit, or merchant cash advance, including 8% that specifically applied for an MCA. Meanwhile, online lenders attracted 29% of financing applicants, up from 17% five years earlier. These findings indicate substantial financing demand, although they do not establish a specific MCA growth forecast for 2027.
Three developments deserve attention:
- Financing demand – Businesses continue to seek capital for operating expenses, expansion and cash flow.
- Digital competition – More applicants are considering online financing providers, increasing the importance of effective client acquisition.
- Borrower expectations – Transparent costs and repayment terms will remain important to funding conversations.
In March 2026, the Federal Reserve Bank of Cleveland reported that 60% of online borrowers faced higher financing costs than they expected. This creates challenges for providers selling expensive financing products. It also creates opportunities for brokers who explain funding terms clearly and qualify merchants before presenting offers. In 2027, effective MCA lead generation will depend on reaching interested businesses and building confidence throughout the sales process.
Which MCA leads should buyers purchase in 2027?
The best MCA leads depend on a lending company’s sales capacity, budget, and funding process. Aged submissions and UCC data offer affordable prospecting volume, while real-time applications provide more immediate business owner interest. Neither category guarantees better returns without effective qualification and follow-up.
Aged MCA leads originate from previous business funding applications. Some merchants have already secured capital, while others may still need financing or additional funding. One TLW aged submission product contains applications from businesses reporting at least $20,000 in monthly revenue. These records are 90-180 days old and include verified email addresses and cellular phone numbers. Their lower price per lead makes them attractive to brokers capable of working larger prospect pools.
Real-time MCA leads offer a different opportunity. One available product collects more than 20 application fields and requires businesses to have operated for at least 12 months. Applicants must report at least $15,000 in monthly revenue and request $20,000 or more in funding. These details support early qualification, but the higher cost per lead (CPL) demands that funding companies respond to the lead quickly and with skilled salespeople.
UCC leads, funding triggers, and response data
UCC leads identify businesses associated with secured financing filings. Funding trigger data relates to business financing credit inquiries, while response data comes from previous business funding campaigns. These sources should not be treated as interchangeable. A filing establishes a financing relationship, not necessarily a current funding request. Similarly, a credit inquiry may signal interest without confirming that the business qualifies for another advance.
For MCA lead buyers, each source offers a different prospecting opportunity:
- UCC filings – These leads identify businesses with recorded secured financing activity.
- Funding triggers – Funding trigger leads highlight businesses associated with recent financing inquiries.
- Response data – These leads identify merchants who previously responded to funding-related marketing.
These records can support targeted outreach efforts, especially for brokers experienced in discussing existing obligations and future capital needs. Funding companies looking to buy MCA leads should understand the age, origin, and available fields before purchasing. For more information in distinguishing between these lead options, read our blog, “UCC Leads vs. Real-Time Applications Data – Which Performs Better For MCA?”
MCA lead pricing and what buyers should budget
MCA lead prices vary based on lead age, source, exclusivity, and qualification depth. Aged applications can cost pennies, while exclusive real-time submissions can exceed $100 per lead. These differences reflect how the information was gathered and delivered, not guaranteed approval or funding. Lead buyers should consider the labor required to convert each record to a client before deciding which lead product provides the best value.
Current TLW product examples illustrate the relative pricing differences:
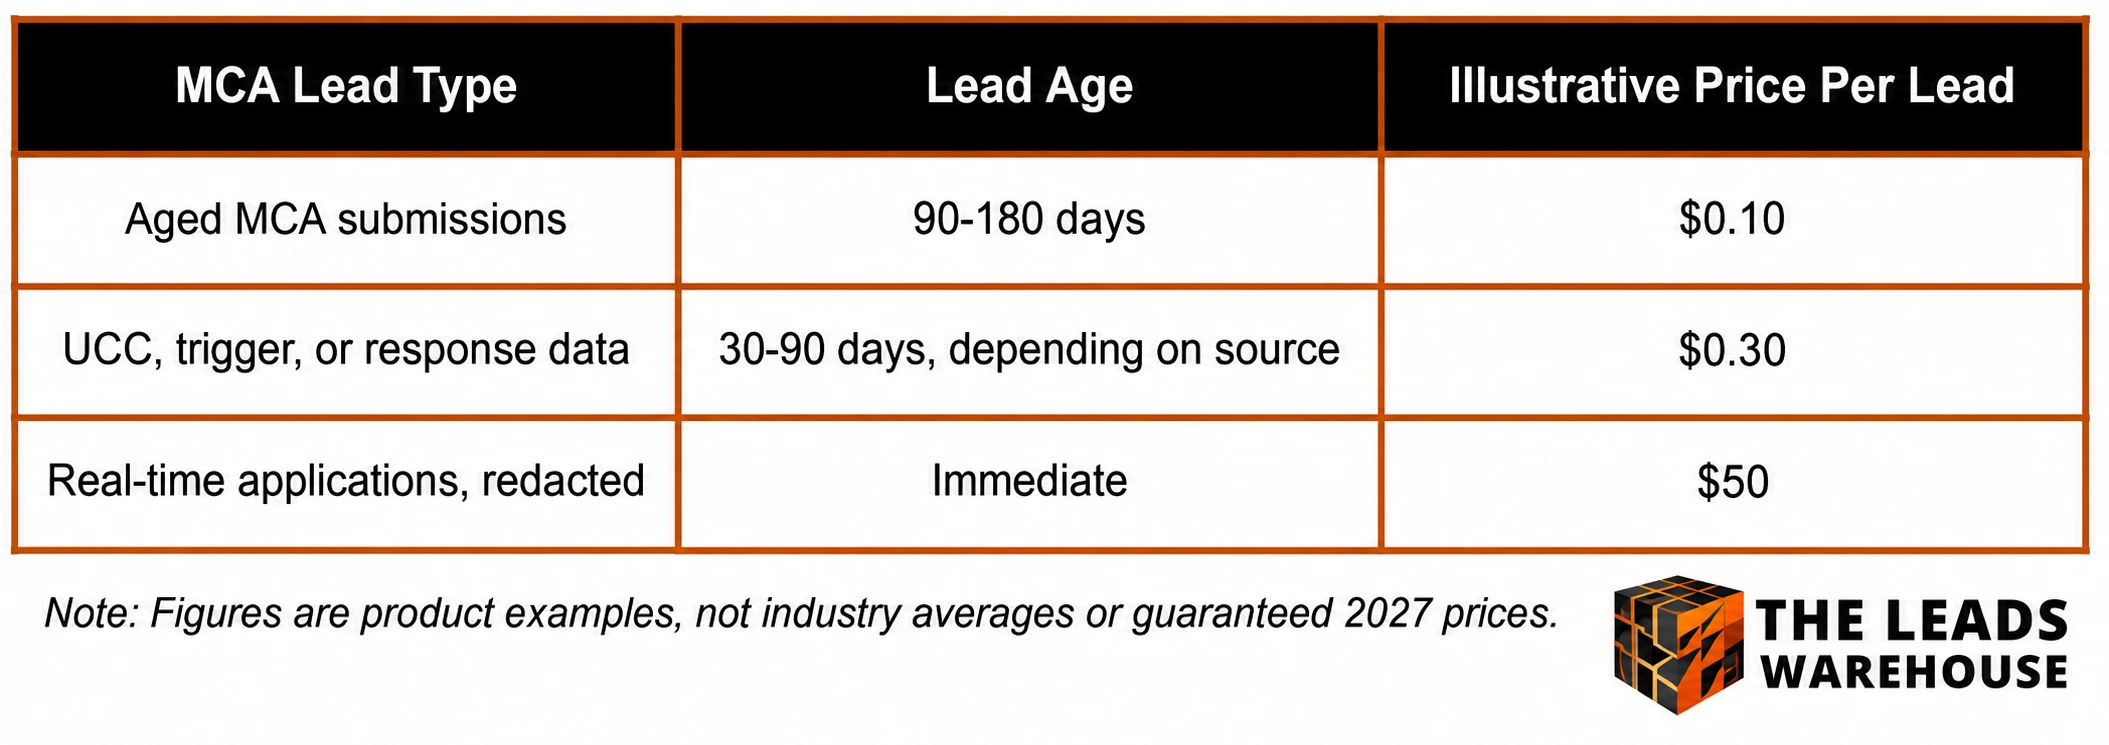
These are current lead product prices, not industry averages or guaranteed 2027 rates. At $0.10 per record, 10,000 aged submissions cost $1,000 before other outreach expenses. Alternatively, a lending company could buy 20 real-time MCA leads at $50 per lead for the same budget. Comparing those purchases requires measuring actual funded deals, not just applications or conversations. For more information on assessing the value and performance of MCA leads, read our blog, “Are MCA Leads Worth It? ROI, Approval Rates And Deal Flow.”
Three proven TLW client process recommendations
Buying merchant cash advance leads is just the first step. Funding companies must effectively work the leads to realize any benefit. Based on more than 20 years of working in the industry, TLW’s experience suggests that successful clients follow these proven processes:
- Work aged leads through a structured two-week cadence. TLW’s aged MCA campaign guidelines recommend three call attempts daily, with contact times rotated throughout the day. Supporting texts and emails should be used only where permitted. A single unsuccessful call provides little evidence about lead quality. The objective is to give each prospect a reasonable opportunity to respond while documenting outreach results. For more information on a recommended multi-channel cadence, read our blog, “TLW.media: The Best MCA and B2B Leads Provider.”
- Contact real-time applicants within eight seconds. TLW’s real-time business funding guidelines recommend immediate outreach, additional attempts on the first day, and a revised script after approximately one week. Fresh applicants should hear a conversation relevant to their recent funding request. Older inquiries require a different approach that confirms whether financing is still needed. Response speed and script selection directly affect the value lead buyers can extract from premium funding applications.
- Evaluate campaigns using documented performance. TLW’s product guidelines require dialer reports, call logs, and delivery metrics when assessing results. Funding companies should also measure completed applications, approvals, funded transactions, and acquisition costs. A low price per lead means little if salespeople cannot reach or qualify merchants. Conversely, expensive leads may justify their price when they produce profitable funding outcomes.
MCA lead compliance and data quality
MCA marketing requires careful handling of business records, contact permissions, and sensitive application information. A public UCC filing does not establish consent for automated calls or texts. Similarly, a prior application should not be assumed to authorize every marketing channel indefinitely. Buyers need to understand the source of each record and apply relevant federal and state requirements before outreach.
Before companies buy merchant cash advance leads, they should conduct a practical review to confirm:
- Data source, lead age, and available qualification fields
- Consent documentation and permitted outreach channels
- Duplicate handling, suppression procedures, and replacement policies
- Secure delivery and storage of sensitive business information
Building a profitable MCA lead strategy for 2027
The strongest acquisition plans will likely combine affordable aged MCA leads, targeted UCC or response data, and selective real-time applications. The Federal Reserve Bank of Kansas City’s Small Business Lending Survey also reported year-over-year growth in new bank lending during the second quarter of 2026, reinforcing the need to compete across financing options. With 38% of surveyed firms applying for loans, credit lines, or MCAs, the opportunity is substantial. Funding companies can schedule a strategy session with The Leads Warehouse to build an acquisition plan around their budget, staffing, and sales capabilities. Are you ready to talk about how you can grow your MCA / business funding sales pipeline?
Ready to Grow Your MCA / Business Funding Client Pipeline?
Get instant access to compliant, high-intent aged and real-time MCA/business funding leads and B2B data.
About the author
James Schulze is the President and CEO of The Leads Warehouse, a marketing data company with over 20 years of experience in bringing lead generation solutions to companies selling into the home, automotive, financial, insurance, health and life, and legal sectors. He works directly with clients to optimize conversion strategies and ROI across multiple verticals.
Connect with James Schulze on LinkedIn:
https://www.linkedin.com/in/james-l-schulze
Read additional market analysis and commentary from James Schulze on Substack:
https://jameslschulze.substack.com
If you are serious about growing your MCA / business funding business, the right blend of sales leads is critical. The Leads Warehouse works with funding companies to maximize their ROI on MCA sales leads. Call 1-800-884-8371 or visit The Leads Warehouse to get started.